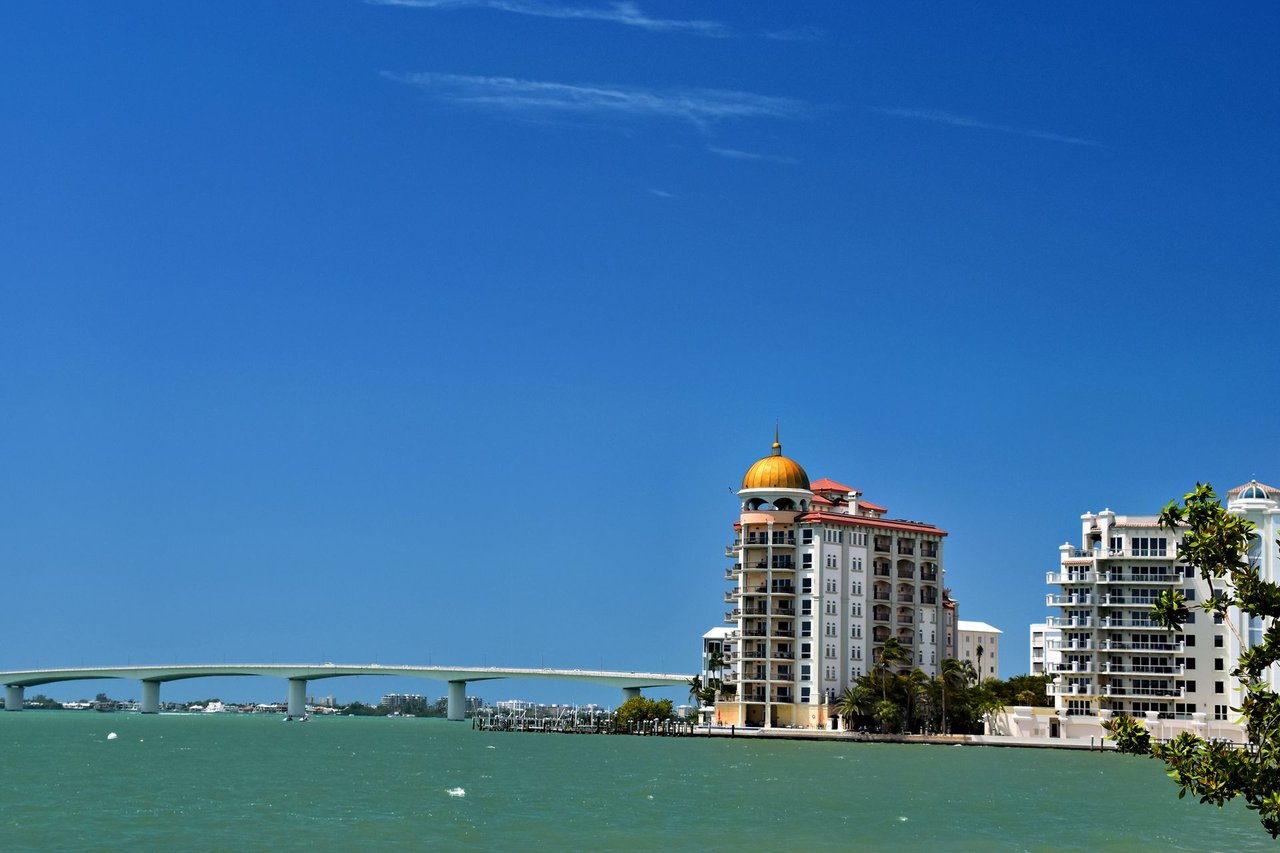
Moving to Sarasota from New York: The Domicile, Tax & Audit Guide for 2027
To move your domicile from New York to Sarasota, you must do two things at once: establish Florida as your true home and show you have left New York domicile behind. File a Declaration of Domicile in Sarasota County, get a Florida driver's license, register to vote in Florida, move your primary life here, and file for homestead if you own and occupy your Sarasota home on January 1 (file by March 1). Spending 183 days outside New York helps with one New York test — it does not, by itself, change your domicile, and it is the mistake that triggers audits.
Figures shown are the most recent published at the time of writing; exemption amounts, caps, and millage are set annually — confirm current-year figures before filing.
New Yorkers are not discovering Sarasota by accident. In 2025, New York was the No. 1 domestic source of moves into Sarasota County, with 1,426 driver-license exchanges — ahead of every other state (Florida Realtors / REALTOR Association of Sarasota and Manatee, revised January 2026). At the $5M+ level, those moves share the same pattern: the home is found quickly; the tax and domicile questions take longer, cost more if they are handled late, and follow you back to New York if they are handled casually.
This guide walks through what actually changes your domicile, what New York looks for if it audits you, the Florida filing deadlines you cannot miss, and the full cost picture — including the costs some relocation posts leave out.
Domicile is your true, permanent home — the place you intend to return to whenever you are away. You can have several residences, but you can have only one domicile. New York starts from the position that once you are domiciled there, you remain domiciled there until you prove you have both left New York and established a new domicile elsewhere. Buying a beautiful home in Sarasota does not meet that test on its own. Neither does spending winters here while keeping your life — doctors, advisors, clubs, cars, and the home you call home — in New York.
That is why sequencing matters for a $5M+ purchase. Your closing date, your January 1 occupancy for homestead, your license and voter-registration dates, and the date you file your Declaration of Domicile all become part of one timeline. If an auditor later asks when you moved, those dates should tell the same story. Build the timeline first, with your CPA and attorney, then buy inside it — not the other way around.
This is the single most misunderstood point in the move, so it deserves plain language. Florida does not impose a 183-day rule to become a resident or domiciliary. The 183-day figure comes from New York law, under its separate statutory residency test: if you maintain a permanent place of abode in New York and spend more than 183 days there in a year, New York can tax you as a resident even if your domicile has moved to Florida.
Domicile and statutory residency are two different tests, and you must plan for both. You can pass the day count and still fail on domicile if your life remains centred in New York. You can also establish Florida domicile and still face New York tax in a given year if you keep a New York home and exceed the day count. Keep a contemporaneous day log — flights, card receipts, and phone records are what auditors ask for — and do not rely on memory a year later.
The takeaway: count your New York days, but do not stop there. Domicile is proved by where your life is, not only by where your calendar says you slept.
New York domicile audits are fact-intensive, and at higher incomes they are common enough that you should assume your file could be read by an auditor. Examiners generally weigh five broad factors together: your home (which home you keep, its size and use, and whether the New York home was sold, leased, or kept available); your active business involvement in New York; your time in each place; your near-and-dear items — the possessions you would move first, from family photos to pets to valuables; and your family connections. No single document wins or loses an audit. Consistency across all five is what makes a move credible.
In practice, consistency looks like this. Home: Sarasota is the home you live in and return to; any New York home is sold, leased, or clearly secondary in size and use. Business: active New York business involvement is reduced, restructured, or documented — not left ambiguous. Time: your day log shows Sarasota as the centre of your year, with New York days tracked against the 183-day test. Near-and-dear items: family photos, pets, valuables, and the possessions that matter most are in Sarasota. Family: household and family life — spouse, dependants, schooling where relevant — aligns with the Sarasota move.
Practically, that means the Sarasota home should function as your home, not as a vacation address: live in it, receive mail there, keep your near-and-dear items there, and use local doctors, dentists, advisors, houses of worship, and clubs where that reflects your real life. If you keep a New York residence, understand how keeping it — and how you use it — will be read. Get advice on that point before you close, not after a notice arrives.
Work through this list with your CPA and attorney and keep dated copies of everything in one file. Order matters less than completeness and consistency — but do the core items promptly after you move, not months later.
Two cautions belong on the checklist itself. First, a Declaration of Domicile alone does not create domicile — it records your intent, which must match your actions. Second, do not backdate anything. Auditors compare license dates, closing dates, moving invoices, and utility records, and a clean, slightly later date is worth far more than an early date that does not hold up.
Florida homestead is the benefit relocating buyers most often leave on the table by missing a deadline. If you own and occupy your Sarasota home as your primary residence on January 1, you may claim homestead for that tax year — but you must file by March 1. Missing March 1 generally means waiting a full year, no matter when you bought.
Homestead reduces the taxable value of your primary home by up to the current year's exemption amount — confirm the current figure with the Sarasota County Property Appraiser. Save Our Homes caps annual growth in assessed value at the lesser of 3% or inflation, so over years at $5M+ the gap between market and assessed value can become substantial. And if you move within Florida and had homestead at your prior Florida home, portability lets you transfer up to $500,000 of your Save Our Homes benefit to the new home, subject to the filing rules and deadlines.
The filing calendar, in one place. Before December 31: if closing near year-end, confirm you can own and occupy as your primary residence on January 1. January 1: own and occupy the Sarasota home as your primary residence — the eligibility date for that tax year. By March 1: file for homestead (and portability, if moving within Florida) with the Sarasota County Property Appraiser — do not miss this deadline. Every year after: your Save Our Homes cap protects you automatically while homestead remains in place.
File with the Sarasota County Property Appraiser as soon as you are eligible, bring the identification and proof of occupancy the office requires, and calendar March 1 the moment you sign a contract that closes near year-end. If your purchase closes in December, the January 1 occupancy question should be part of the closing conversation — not a January surprise.
The headline is real: Florida has no state income tax, no separate state capital-gains tax, and no state estate tax. For a high earner leaving New York's combined state and city burden, that difference is often the financial engine of the move. But an honest guide must put the offsets on the same page, because your carrying costs in Sarasota will not be close to zero — and posts that pretend otherwise lose the trust of exactly the buyers they hope to attract.
Property tax: You will often see Sarasota County's operating millage quoted on its own. That is only one line of the bill. The combined millage — county, city where applicable, schools, and special districts — is far higher than the county operating line alone; model your bill from the specific property's actual tax record. Ask for the prior owner's tax bill and a no-homestead estimate before you offer: the seller's capped assessment does not transfer to you.
Insurance: Waterfront and near-water homes at this level require a serious insurance conversation — wind, hurricane deductibles (commonly a percentage of dwelling value, not a flat amount), and flood. Federal flood coverage caps well below replacement cost at this price point, so many $5M+ owners carry private or excess flood coverage. Get bindable quotes during your inspection period, not after closing.
HOA, condo, and district charges: Condominium assessments, HOA fees, and in some communities community development district (CDD) charges on the tax bill can be material at luxury buildings and master-planned communities. Read the full budget and reserve position, not just the monthly fee. The right comparison is total annual carry — tax, insurance, HOA or condo fees, and district charges — against your total New York carry. For many buyers the Florida total still wins clearly. It wins honestly, with the numbers shown.
Buying at $5M+ as a relocating New Yorker, sequence matters. Put the professionals in the right order. First, a short domicile consultation with your CPA and a Florida estate or tax attorney — before you write an offer — so your closing date, entity or title choices, and New York home decision fit one plan. Second, insurance quotes early, while you can still negotiate or walk. Third, a purchase search focused on how you will actually live here full-time — primary-home function, not vacation function — because that lived reality is both the point of the move and the evidence that supports it.
Finally, keep the file. Closing statement, Declaration of Domicile, license, voter card, homestead receipt, moving invoices, and your day log belong together. If New York never asks, you have lost an hour of filing. If it does ask, you have your answer ready.
How many days can I spend in New York after I move to Sarasota? Under New York's statutory residency test, spending more than 183 days in New York in a year while maintaining a permanent place of abode there can make you taxable as a New York resident for that year — even with Florida domicile. Domicile itself has no day-count safe harbour, so track your days and take advice on both tests.
Does buying a home in Sarasota automatically make Florida my domicile? No. A purchase is evidence, not a conclusion. New York looks at your home, business ties, time, near-and-dear possessions, and family factors together. The checklist in this guide — Declaration of Domicile, Florida license and voter registration, homestead, and a primary life actually lived in Sarasota — is what makes the purchase credible as a domicile change.
When do I file for Florida homestead, and what do I get? You must own and occupy the home as your primary residence on January 1 and file by March 1 of that tax year. Homestead reduces the taxable value of your primary home by up to the current year's exemption amount — confirm the current figure with the Sarasota County Property Appraiser — and the Save Our Homes cap — the lesser of 3% or inflation — limits how fast your assessed value can rise. If you are moving within Florida, ask about portability of up to $500,000 of Save Our Homes benefit.
Will New York audit my move? It might, and higher-income movers should plan as if it will. Audits focus on whether you truly left New York domicile and, separately, on your day count if you kept a New York home. A contemporaneous day log, consistent dates across your documents, and advice taken before the move are your best preparation. This guide is general information, not a prediction about any individual case.
Is Sarasota really cheaper if property tax, insurance, and HOA still apply? Often yes — but compare totals, not headlines. Florida has no state income, capital-gains, or estate tax, while Sarasota carrying costs include property tax modelled from the specific property's actual tax record — the combined millage is far higher than the county operating line alone — insurance (including flood where needed), and HOA, condo, or district charges. A worked, property-specific carry estimate before you offer is the only honest way to know your number.
Ready to talk it through? Schedule a call to discuss your goals with Andrea Stultz Wood, Engel & Völkers / Stultz Wood Group — Sarasota luxury real estate, waterfront and golf homes.
Florida Realtors / REALTOR Association of Sarasota and Manatee license-exchange data, revised January 2026 — New York: 1,426 exchanges into Sarasota County in 2025 (No. 1 domestic feeder). Sarasota County Property Appraiser — homestead filing calendar (own and occupy on January 1, file by March 1); exemption amounts, the Save Our Homes cap, and millage are set annually — confirm current-year figures with the Sarasota County Property Appraiser and Tax Collector before filing.
Disclaimer: This article is general information about relocating to Sarasota and Florida domicile concepts. It is not tax, legal, or financial advice and does not create an advisor-client relationship. Tax law, exemption amounts, millage rates, and deadlines change, and New York domicile determinations depend on individual facts. Consult your CPA and a qualified Florida and New York attorney about your specific circumstances before acting.
Stay up to date on the latest real estate trends.
For buyers purchasing at $5M and above, the move is not just a home search. It is a domicile decision - and New York will test whether you really made it.
Here are several of the standout properties currently available across the state.
Downsize your home to maximize your financial gain and secure your future with these expert tips.
To express our gratitude for the heart of the home and share the joy of the season with you.
This group is a major reason why. Their production is awe-inspiring.”
As we step into 2024, we are bidding farewell to the recently popular ultra-minimalist look.
Stultz Wood Group believes great things happen when talented people come together. Discover a team built on trust, collaboration, and a shared commitment to delivering an exceptional real estate experience.
STULTZ WOOD GROUP
ANDREA WOOD
VICTORIA STULTZ
22 S Links Ave Sarasota, FL 34236