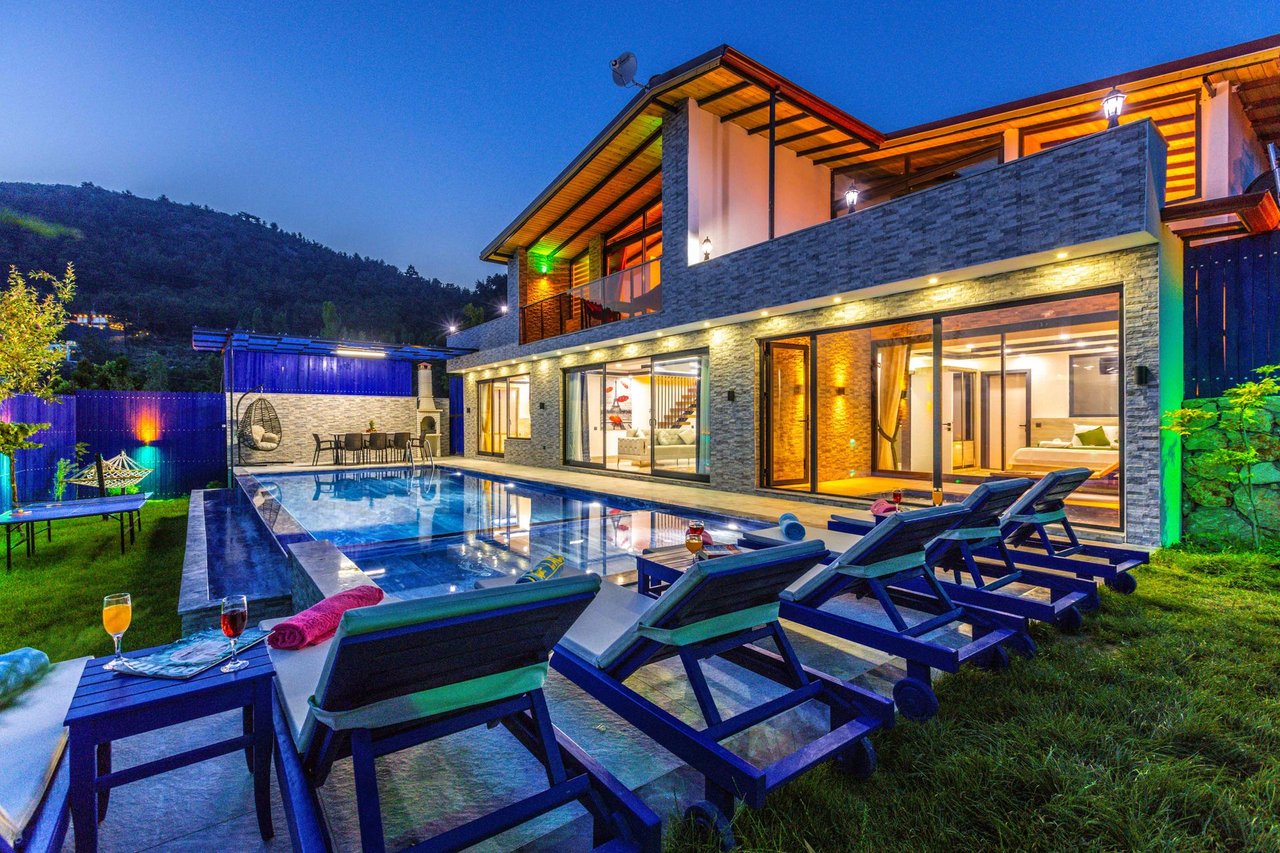
The True Carrying Cost of a $5M Sarasota Home: The Five Lines to Model Before You Offer
The true carrying cost of a $5M Sarasota home is not a single tax rate. Budget from the specific property's actual tax record — the combined millage is far higher than the county operating line alone — plus insurance researched per property (Florida homeowners insurance premiums rose again in 2025, according to the Florida Office of Insurance Regulation), HOA, and, in communities such as Lakewood Ranch, CDD charges that sit on the tax bill.
Portals show you a purchase price and hide the annual bill. Detailed relocation content that ranks in Sarasota wins readers by publishing the true monthly cost: tax, insurance, HOA, and CDD together. This post does that for a $5M purchase as a structure guide — the five lines to model — with no worked dollar totals. Where a real number can only come from the specific property — insurance above all — this post says so instead of guessing.
Start with the honesty gap in most Sarasota content. Many posts quote Sarasota County's operating millage on its own, and stop there. It is only one line of the bill: the combined millage — county, city where applicable, schools, and special districts — is far higher than the county operating line alone; model your bill from the specific property's actual tax record. On a $5M home, the property-tax line is a substantial five-figure annual cost — model it from the specific property's assessed value and district, and ask for the prior owner's tax bill and a no-homestead estimate before you offer. Homestead, where the home is a primary residence, reduces taxable value by up to the current year's homestead exemption amount — confirm the current figure with the Sarasota County Property Appraiser, and the Save Our Homes cap — the lesser of 3% or inflation — limits how fast assessed value can rise each year.
Florida homeowners insurance premiums rose again in 2025, according to the Florida Office of Insurance Regulation. Beyond that verified direction, this post deliberately does not quote a 'typical' premium for a $5M home: the research flagged available averages as non-luxury or single-source, and a waterfront $5M premium depends on elevation, construction, roof, openings, and flood zone. What can be stated is deductible exposure. Florida hurricane deductibles are typically a percentage of dwelling coverage — at $5M+ values that is a six-figure exposure to reserve against. Budget the reserve; get a high-value broker indication on the actual house during diligence.
If the home is waterfront or in a flood zone, add flood coverage as its own line. NFIP caps at $250,000 building and $100,000 contents, so $5M+ owners research private and excess flood above it. Sarasota County participates in FEMA's Community Rating System, which earns policyholders a discount on NFIP premiums — confirm the current discount with your broker. Whether a specific home needs or qualifies for particular coverage is a broker question, property by property — but leaving flood at $0 in a carrying-cost model for a waterfront home is the single most common budgeting error incoming buyers make after the 2024 storms. Elevation — covered in our waterfront buyer's guide — is what connects this line to the purchase decision: the certificate you request before contract is the same document your broker prices from.
HOA costs vary so widely by community that no responsible figure exists without the building's own schedule. Single-family waterfront may have a modest HOA or none; golf communities separate HOA dues from club membership — a distinction current Sarasota golf content stresses, because bundled-golf communities and private clubs (Concession, Ritz-Carlton Members Club, Longboat Key Club) structure costs completely differently. Ask for the full HOA schedule, reserve status, and any pending assessments in writing.
In master-planned communities such as Lakewood Ranch and Waterside, Community Development District (CDD) charges sit on the tax bill, not on the HOA invoice — a detail the research specifically flags because buyers comparing a Lakewood Ranch home with a barrier-island home miss it and understate the Ranch's annual cost. When you compare a $5M waterfront purchase with a golf-community purchase in The Oaks, Founders Club, or Laurel Oak — Stultz Wood Group's bread-and-butter golf communities, which trade at their natural, mostly under-$5M prices — put CDD, HOA, and club lines side by side for each specific property. The comparison only works property by property, with documents, not with community averages.
A defensible $5M carrying-cost model has five researched lines: (1) property tax modelled from the specific property's assessed value and district, less homestead where eligible; (2) homeowners insurance quoted on the actual house; (3) flood structured above the NFIP cap where the property requires it, with the hurricane deductible reserved; (4) HOA from the community's own schedule, plus club costs where golf or beach-club life is part of the purchase; and (5) CDD where the community levies it. Sarasota's overall cost of living sits near the national average, with housing and insurance doing the heavy lifting. Build the model before you offer, and the $5M purchase holds no annual surprises.
How much are property taxes on a $5M home in Sarasota? On a $5M home, the property-tax line is a substantial five-figure annual cost — model it from the specific property's assessed value and district, and ask for the prior owner's tax bill and a no-homestead estimate before you offer.
What is CDD in Lakewood Ranch and is it part of HOA? CDD (Community Development District) charges in communities such as Lakewood Ranch and Waterside sit on the tax bill, not the HOA invoice, per the research. Check the specific property's tax bill and HOA schedule separately.
How much is homeowners insurance on a $5M Sarasota home? There is no credible single figure in the research — available averages were flagged as non-luxury or single-source, so this post does not quote one. Florida homeowners insurance premiums rose again in 2025, according to the Florida Office of Insurance Regulation. Get a high-value broker indication on the specific house, and budget the hurricane deductible as a reserve.
What HOA should I expect in a Sarasota luxury condo? HOA costs vary so widely by community that no responsible figure exists without the building's own schedule — request the full HOA schedule, reserve status, and any pending assessments in writing.
Does homestead reduce taxes on a $5M Sarasota home? Yes, where the home is your primary residence: homestead reduces taxable value by up to the current year's homestead exemption amount — confirm the current figure with the Sarasota County Property Appraiser, and the Save Our Homes cap — the lesser of 3% or inflation — limits how fast assessed value can rise each year, with up to $500,000 of benefit portable within Florida. File by March 1 after occupying on January 1.
Ready to talk it through? Schedule a call to discuss your goals with Andrea Stultz Wood, Engel & Völkers / Stultz Wood Group — Sarasota luxury real estate, waterfront and golf homes.
Sarasota County property tax structure — the combined millage (county, city where applicable, schools, and special districts) is far higher than the county operating line alone; model from the specific property's actual tax record. Florida Office of Insurance Regulation — Florida homeowners insurance premiums rose again in 2025; no typical $5M premium is quoted because available averages are non-luxury or single-source. NFIP caps ($250,000 / $100,000) — federal program limits. Sarasota County participates in FEMA's Community Rating System, which earns policyholders a discount on NFIP premiums — confirm the current discount with your broker. Florida hurricane deductibles are typically a percentage of dwelling coverage. Homestead / Save Our Homes / portability mechanics — exemption and cap amounts are set annually; confirm current figures with the Sarasota County Property Appraiser; $500,000 portability. CDD charges sit on the tax bill in Lakewood Ranch/Waterside. Sarasota's overall cost of living sits near the national average in current guides.
Disclaimer: This post is general information about published tax rules and market data, not tax or legal advice. Tax outcomes depend on your full situation. Consult your CPA and a Florida tax attorney before making domicile, homestead, or sale decisions. This post is also general information about published insurance structures, not insurance advice. Coverage, eligibility, and pricing depend on the specific property and carrier. Consult a licensed Florida insurance broker for high-value homes before binding or changing coverage.
Stay up to date on the latest real estate trends.
Stultz Wood Group believes great things happen when talented people come together. Discover a team built on trust, collaboration, and a shared commitment to delivering an exceptional real estate experience.
STULTZ WOOD GROUP
ANDREA WOOD
VICTORIA STULTZ
22 S Links Ave Sarasota, FL 34236